Product design case study · In development

Money, made yours.

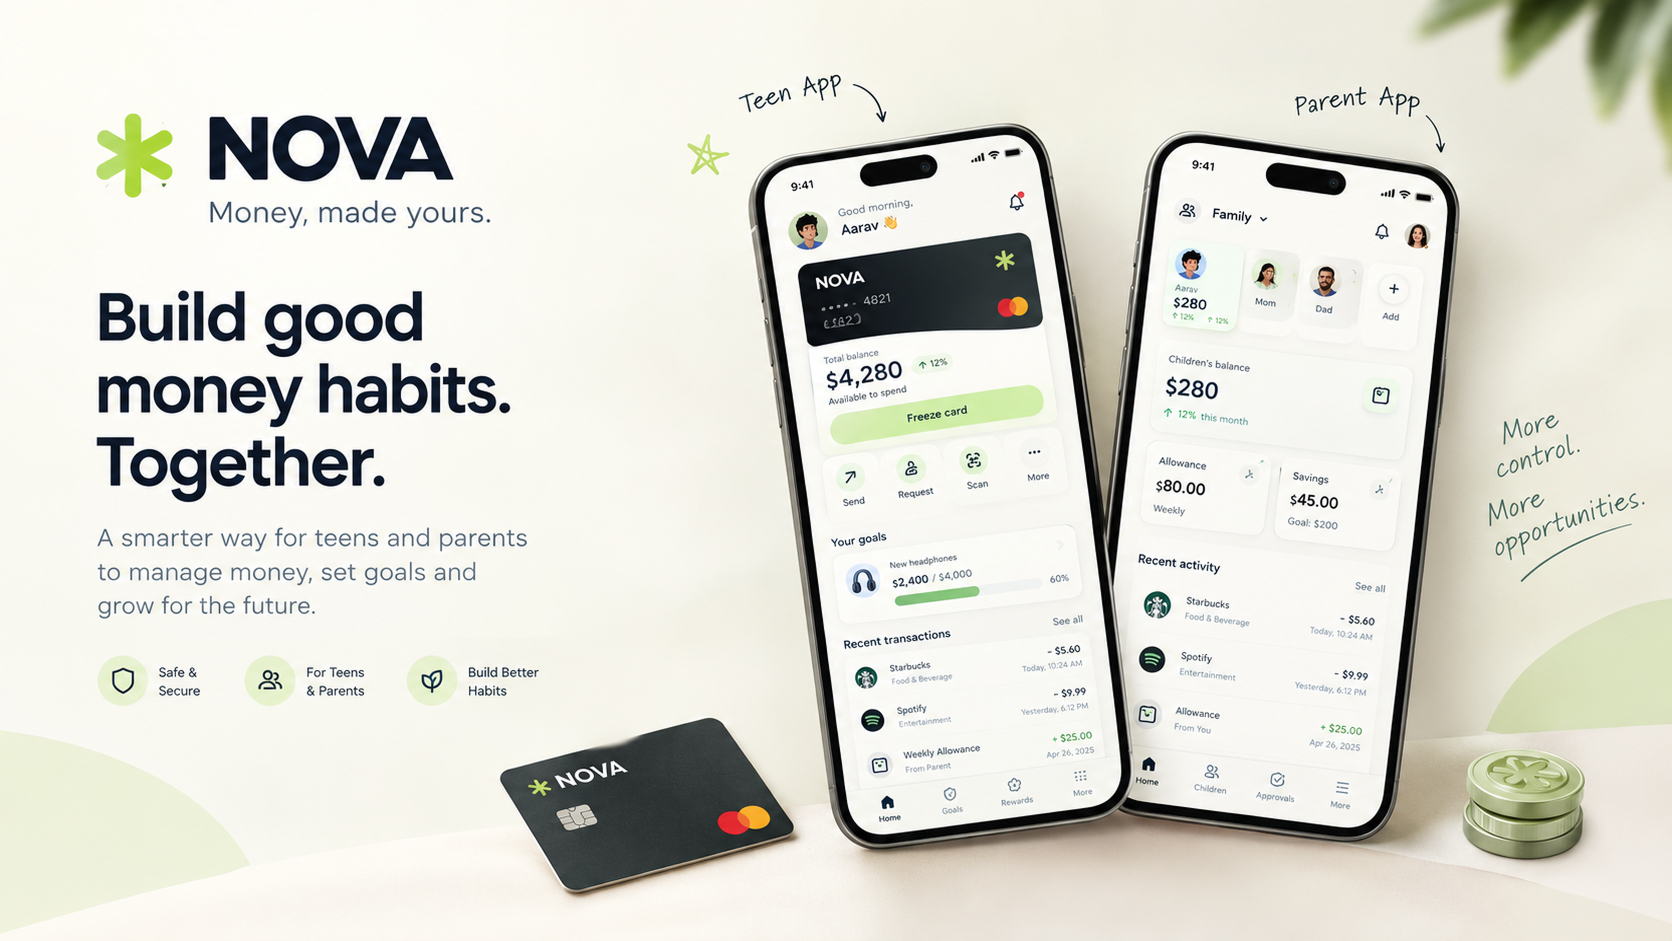
NOVA is a youth-focused financial experience designed around a simple tension: teenagers want independence with money, while parents want confidence without constant control. NOVA connects a teen mobile experience with a parent dashboard through one clear product model.

NOVA Device
ProductNOVA
PlatformsTeen mobile · Parent dashboard
FocusProduct UX · Fintech · Youth
TypeProduct in development
PRODUCT VISUALS

One product, two perspectives.

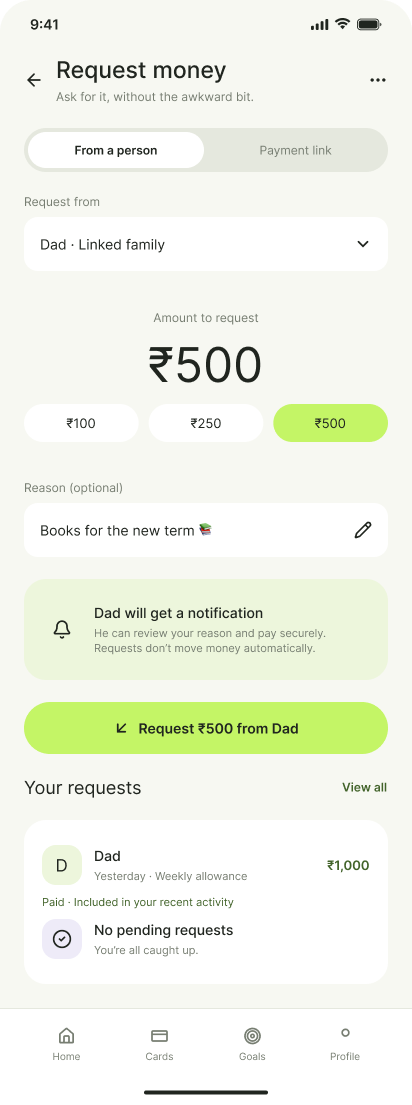
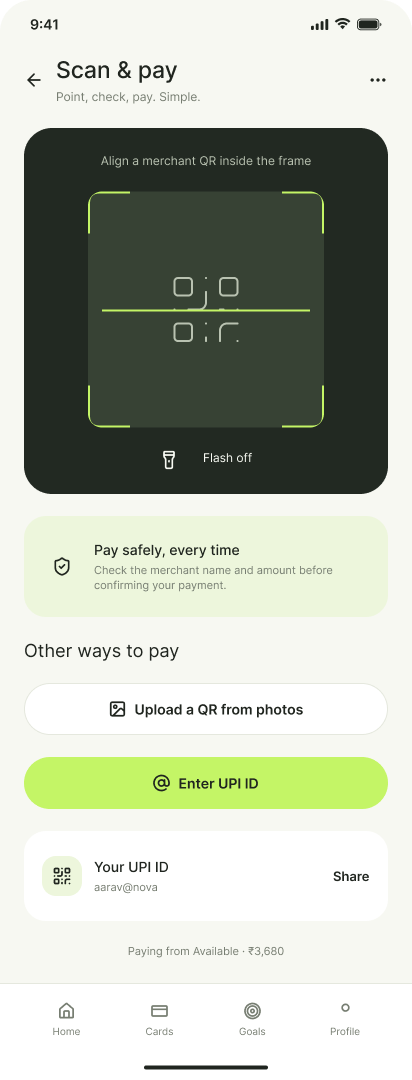
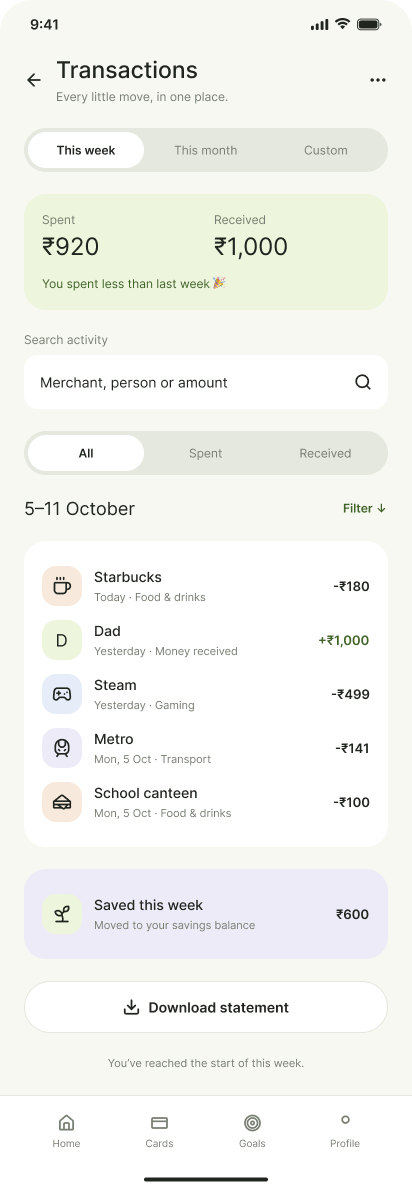
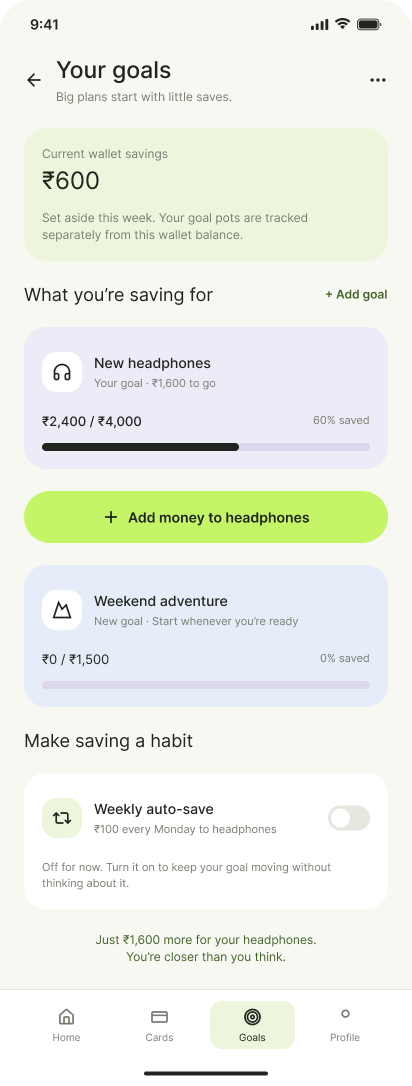
NOVA connects a teen's everyday money experience with a parent's need for visibility and guidance. The interface stays consistent across both surfaces while the jobs-to-be-done remain distinct.

01

The 60 second story

NOVA was conceived as a youth-finance product that treats money management as an everyday learning experience rather than a miniature version of traditional banking.

The product

Spend, save and learn on the teen side. Fund, understand and guide on the parent side.

The teen experience centers on balance, card activity, sending money, savings goals, spending insights, missions and rewards. The parent experience focuses on allowances, child-level patterns, controls, approvals, savings and family activity.

02

The problem is a relationship, not just a transaction.

A teen may care about whether they can pay, save for something they want or understand where their money went. A parent may care about allowance, spending patterns, safety and whether a larger purchase needs attention.

Teenagers need ownership

The product should feel like the teen's money experience, not an adult banking app with brighter colors.

Parents need confidence

Parents need enough context to guide decisions without having to inspect every transaction manually.

Money needs context

A balance alone does not explain behavior. Goals, spending patterns and simple insights help turn numbers into understandable decisions.

Controls need clarity

Limits, approvals and card controls should explain what will happen before the user commits to a setting or decision.

Research approach: Product decisions are framed through category review, competitive analysis and UX synthesis. Scenario walkthroughs, heuristic review and cross-screen consistency checks help assess the current design. This case study does not claim completed user interviews or live user testing unless those activities have actually been conducted.
03

From category patterns to an opportunity.

Existing youth-finance products commonly combine spending, saving, parental visibility and controls. NOVA's opportunity is to make those capabilities feel like one understandable progression: Spend → Understand → Save → Learn.

Category synthesis

The product becomes more useful when financial information teaches the next decision.

Instead of treating insights as a separate analytics area, NOVA connects transactions to understandable patterns, goals and challenges. Parents receive a different interpretation of the same underlying activity.

04

One mental model across two experiences.

The product architecture stays connected even though the interfaces are intentionally different.

Teen

Spend · Save · Learn

  • See available money quickly
  • Make everyday payments
  • Understand spending
  • Build savings goals

Parent

Fund · Understand · Guide

  • Send and schedule allowance
  • See patterns before raw activity
  • Set understandable controls
  • Approve larger purchases
01

Fund

Money enters the teen experience through allowance or transfers.

02

Spend

The teen uses the card or sends money in everyday situations.

03

Understand

Transactions become categories, patterns and simple insights.

04

Save

Goals turn future purchases into visible progress.

05

Guide

Parents can encourage, control or approve when context requires it.

05

The teen experience.

Fifteen screens form a complete everyday money loop, from onboarding and balance to payment, savings, learning, controls and security.

01Onboarding

Introduce ownership, spend/save/learn and parent connection.

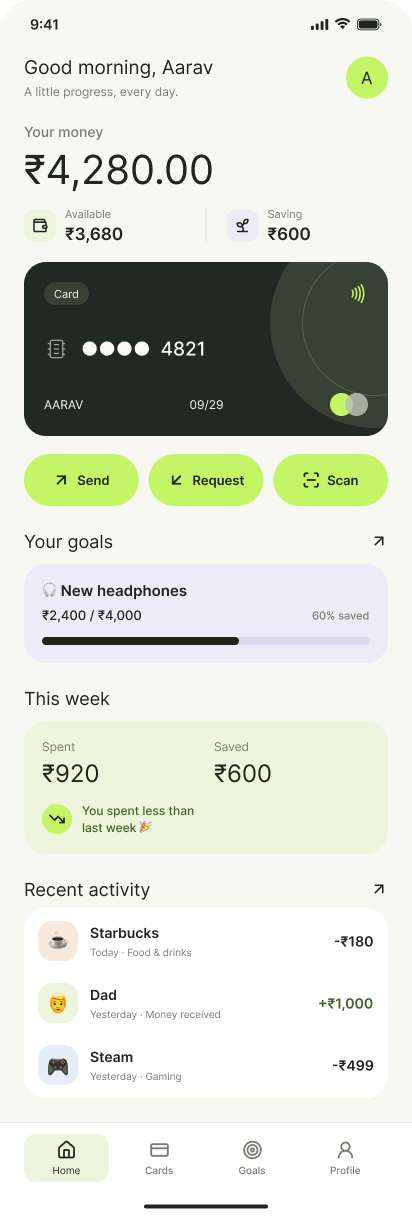
02Home

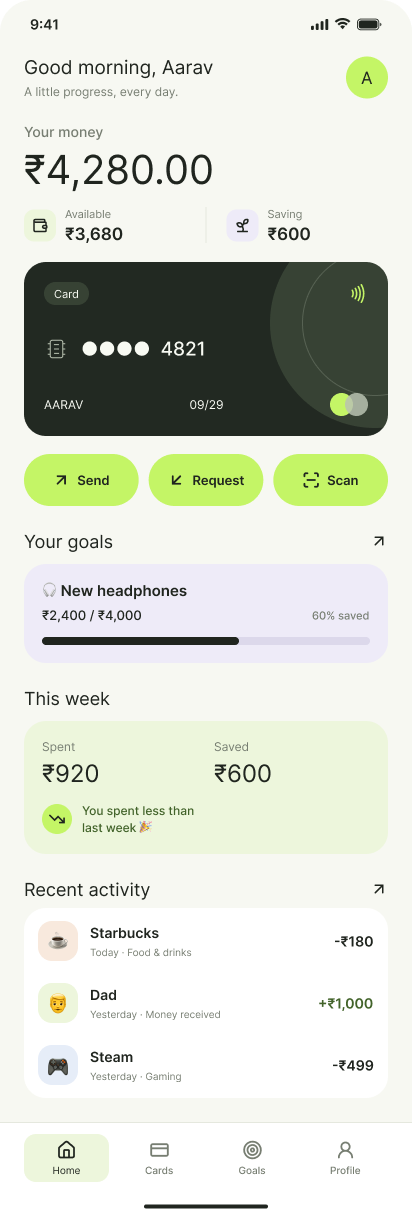
Balance, card, quick actions, goals, insight and recent activity.

03Card

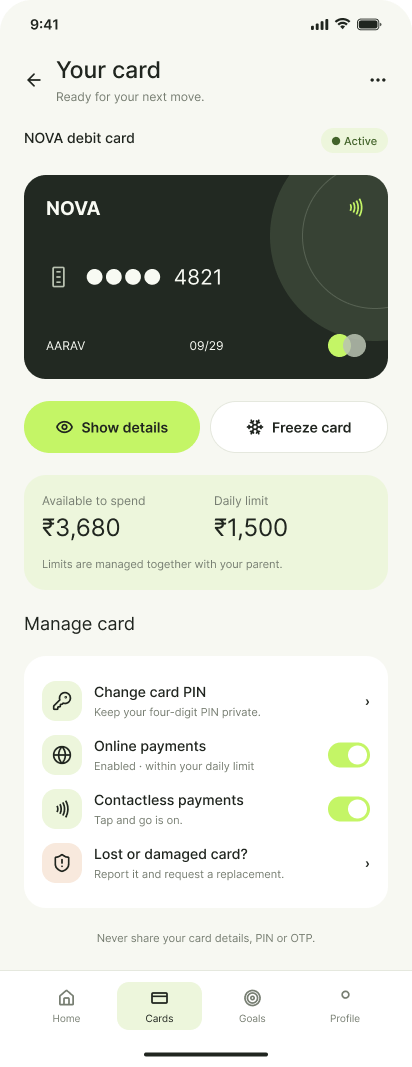
Card status, freeze action, limits and payment settings.

04Send Money

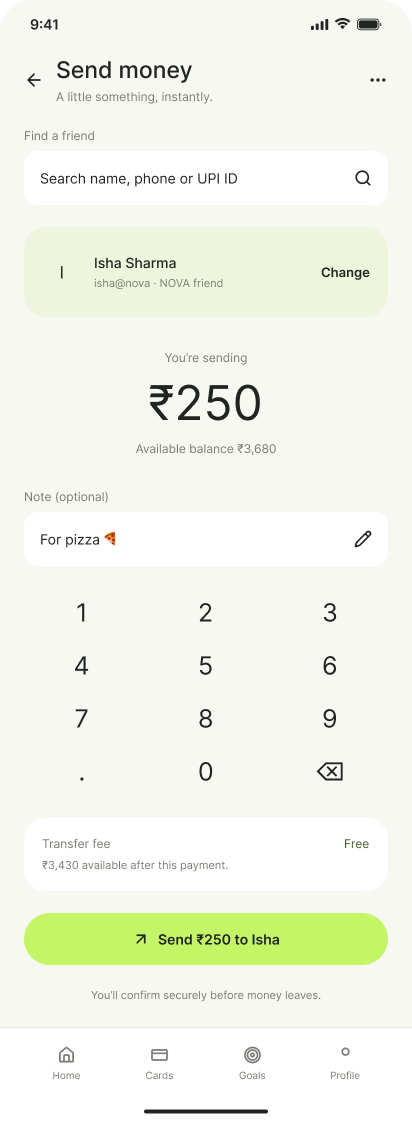
Recipient, amount, note and confirmation flow.

05Payment Confirmation

Merchant, amount, source and final payment action.

06Payment Success

Clear confirmation and transaction details.

07Transactions

All, income and spend with grouped activity.

08Transaction Detail

Merchant, amount, category, payment method and issue reporting.

09Savings Goals

Goal progress, target amounts and create-goal action.

10Goal Detail

Target, progress, deadline and contribution pattern.

11Spending Insights

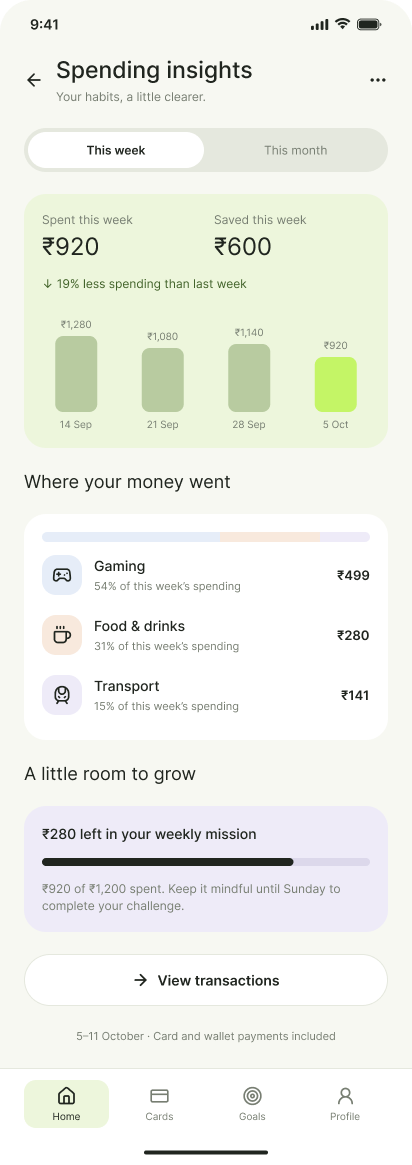
Monthly spend, categories, comparison and simple insight.

12Money Mission

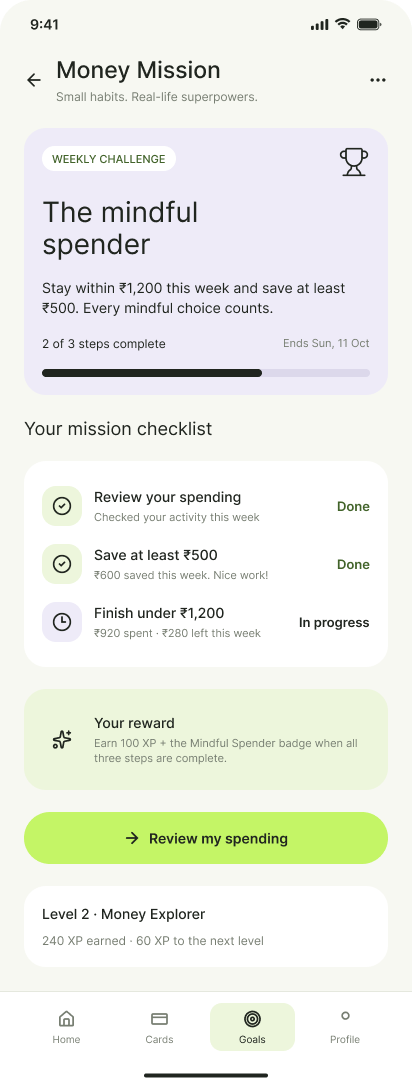
Weekly challenge with progress, remaining amount and deadline.

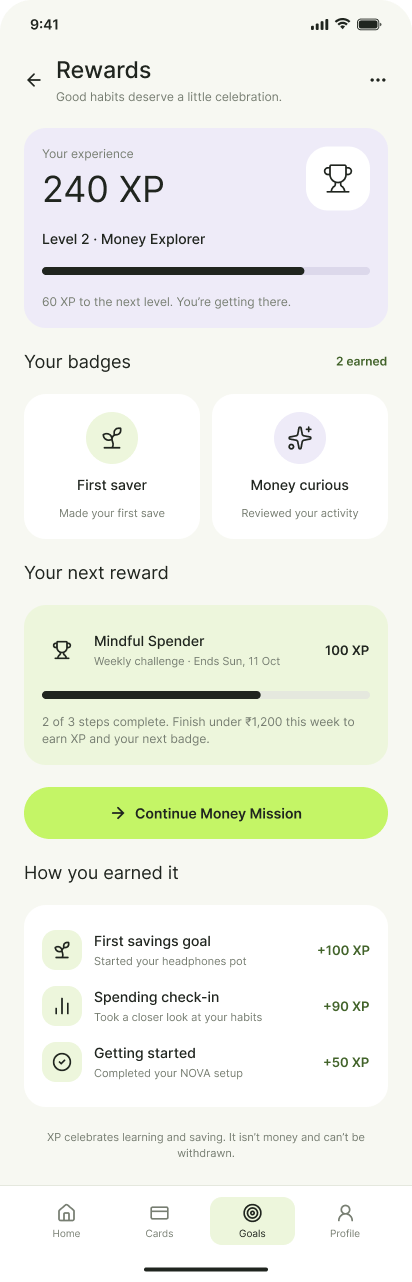
13Rewards

XP, level, rewards and achievements.

14Card Controls

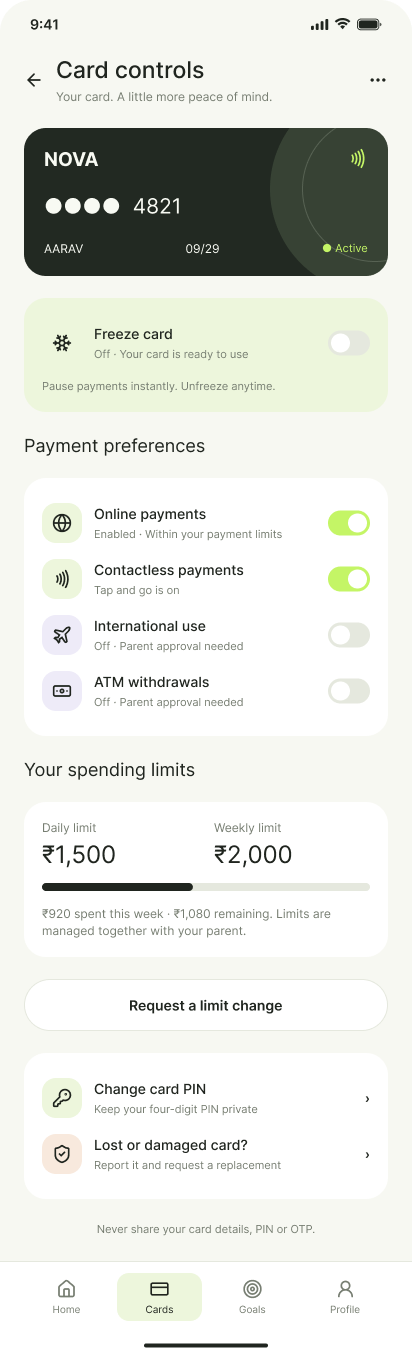
Freeze, online payments, ATM, international and limits.

15Profile & Security

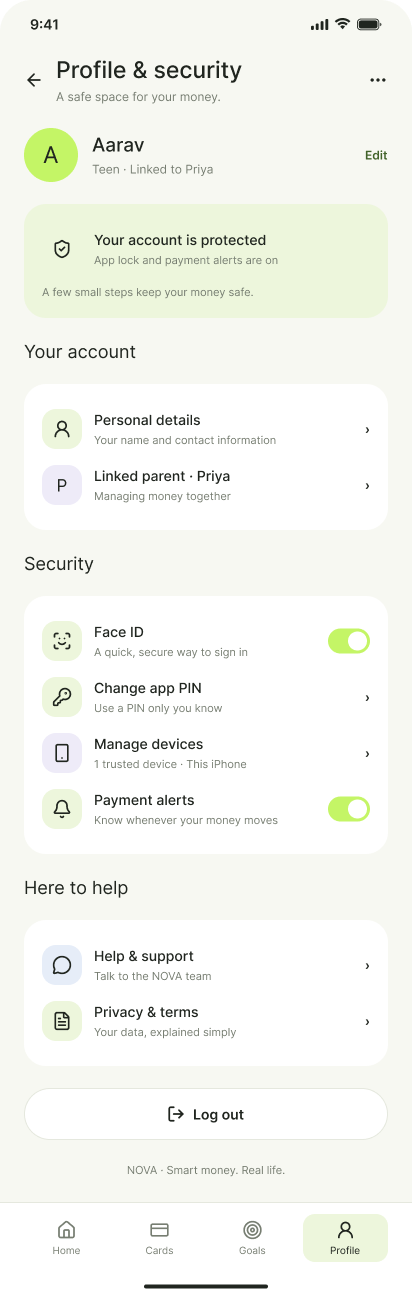
Personal details, biometrics, notifications and support.
06

The parent experience.

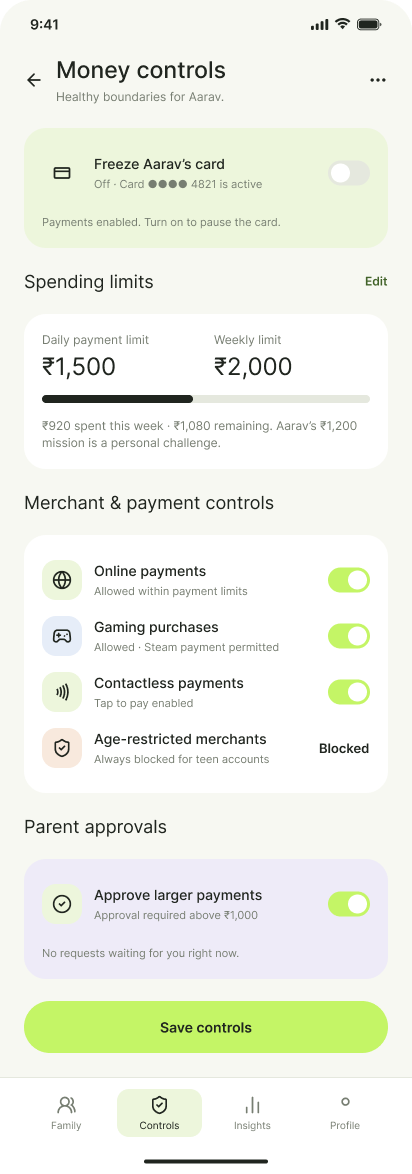
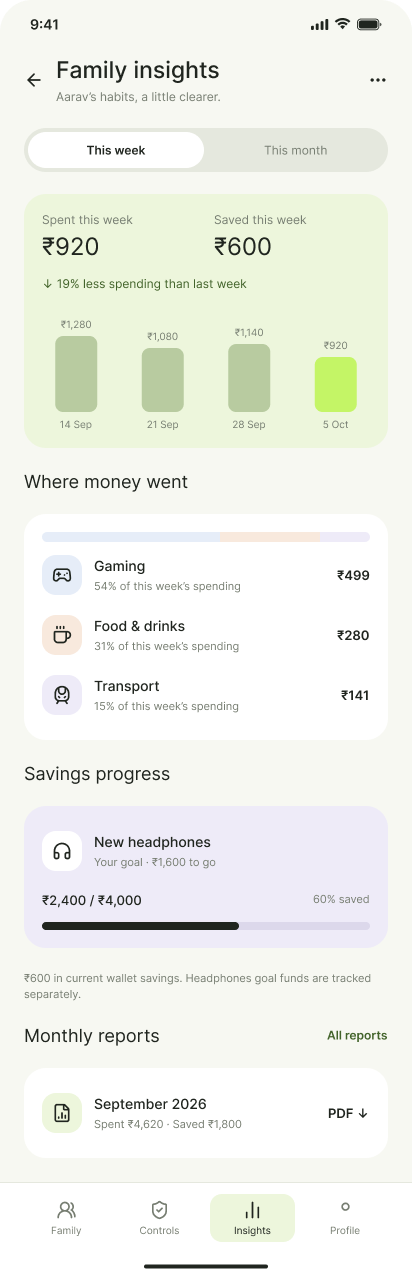
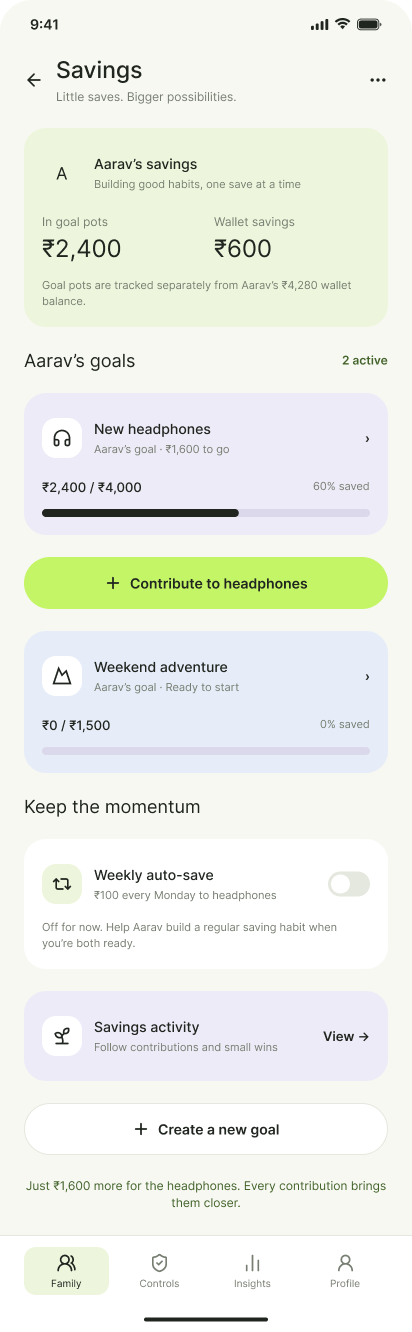
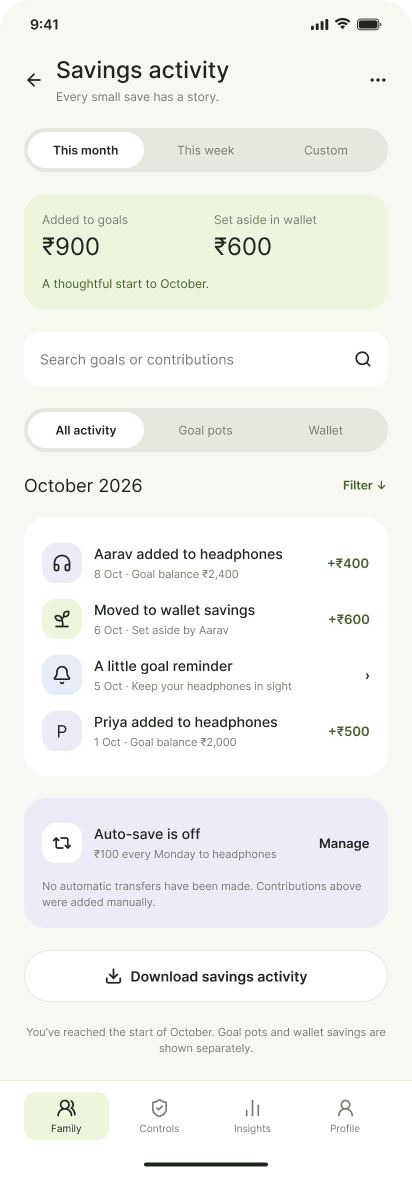
Fourteen screens give parents a calm overview, child-level context, funding tools, controls, approvals, savings guidance and account management.

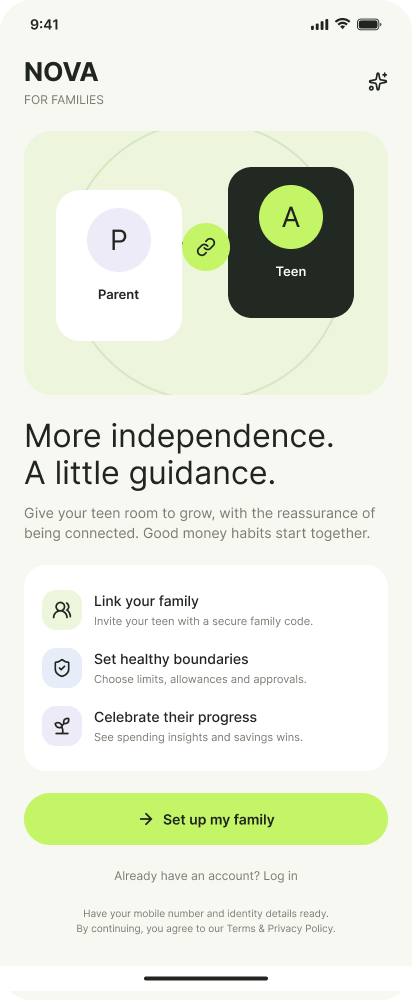
01Parent Onboarding

Explain independence, visibility and guidance.

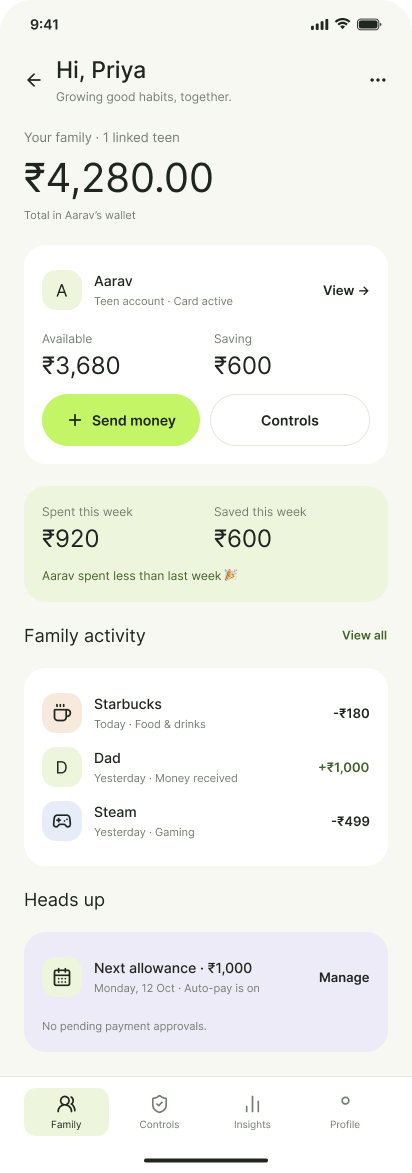
02Dashboard

Family overview and what needs attention.

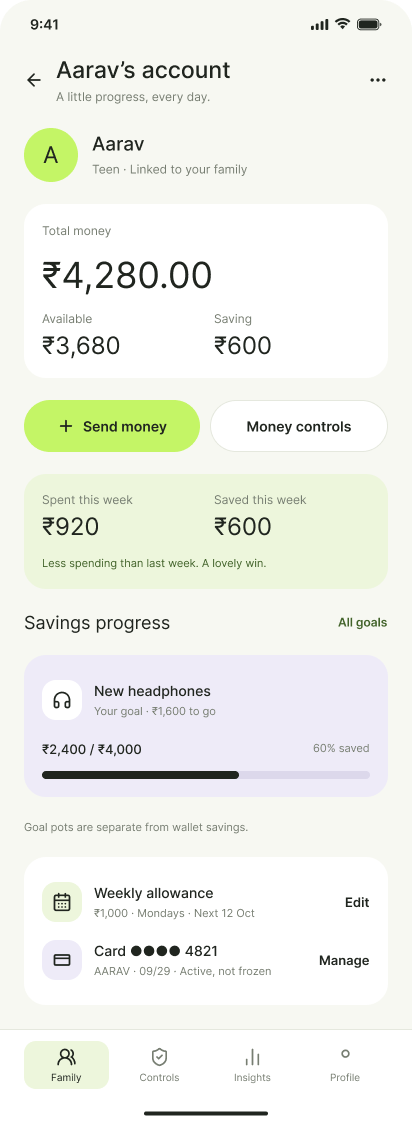
03Child Detail

Balance, spending, savings, allowance and patterns.

04Send Money

Send funds to a selected child with context.

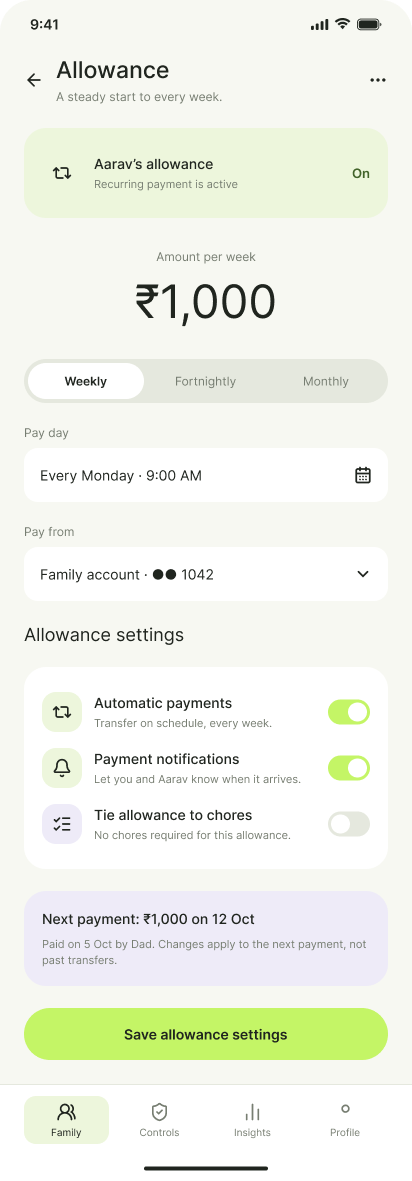
05Allowance

Configure recurring amount, schedule and notifications.

06Money Controls

Limits, payment types, approvals and merchant categories.

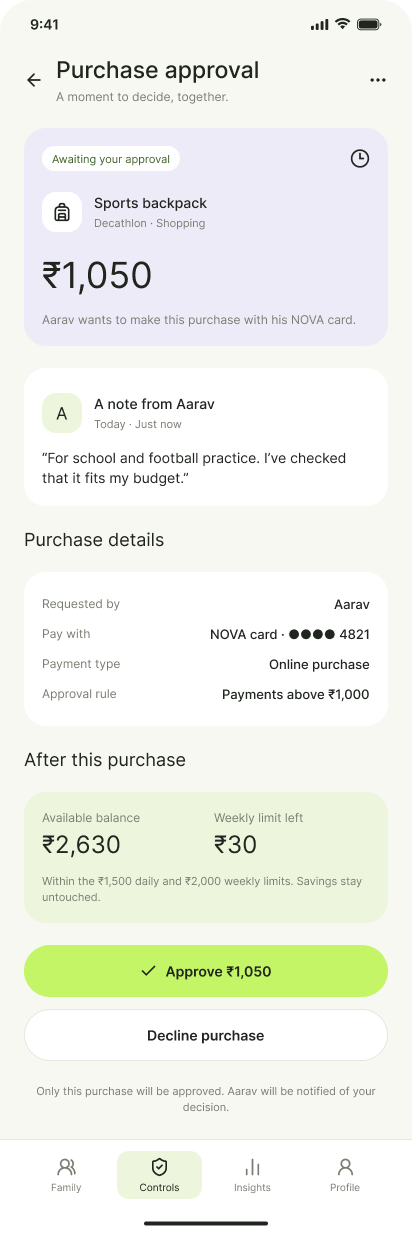
07Purchase Approval

Understand amount, merchant, reason and post-purchase balance.

08Insights

Family spending and savings trends.

09Savings

Goals across children and progress toward targets.

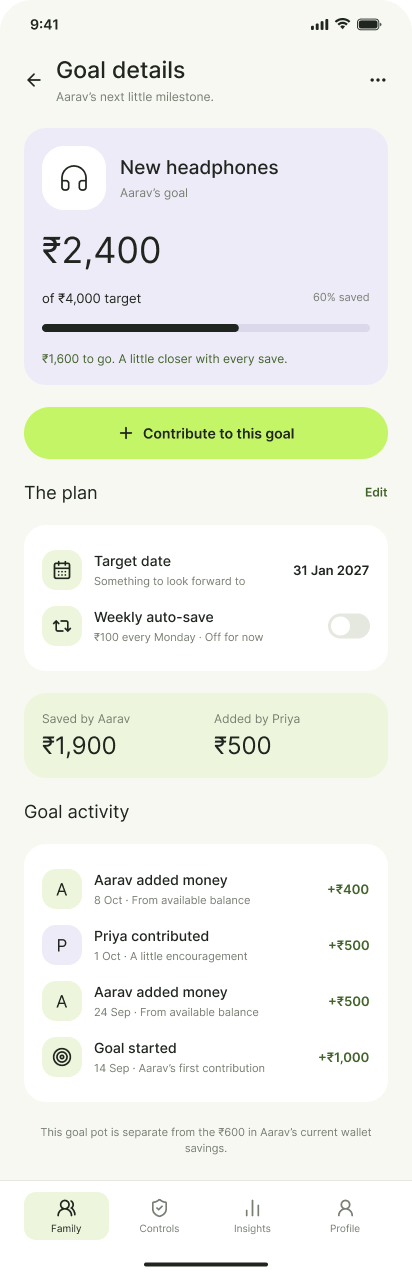
10Goal Detail

Support contributions and encouragement.

11Activity

Money, children, goals and approval history.

12Notifications

Prioritize approvals and meaningful updates.

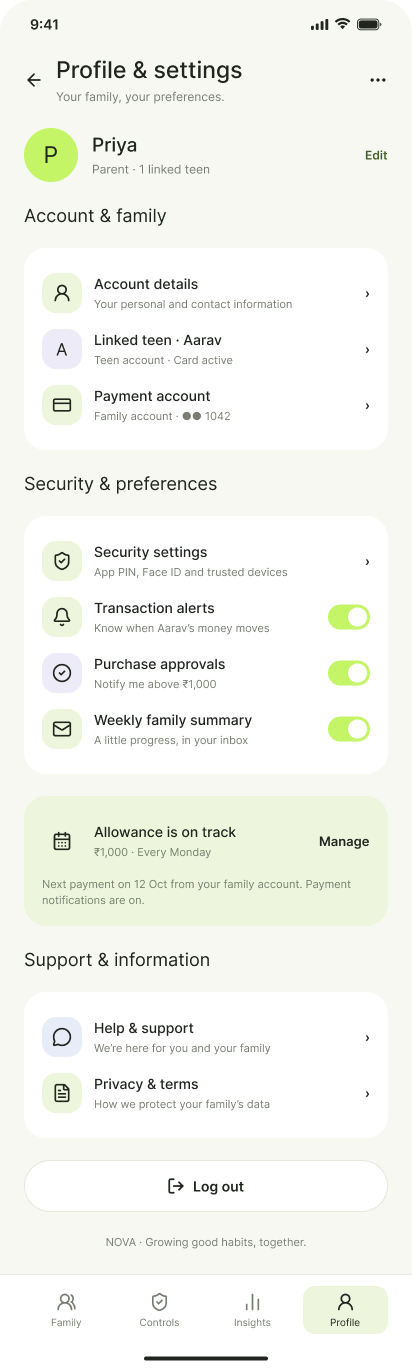
13Profile & Settings

Family, security, notifications and support.
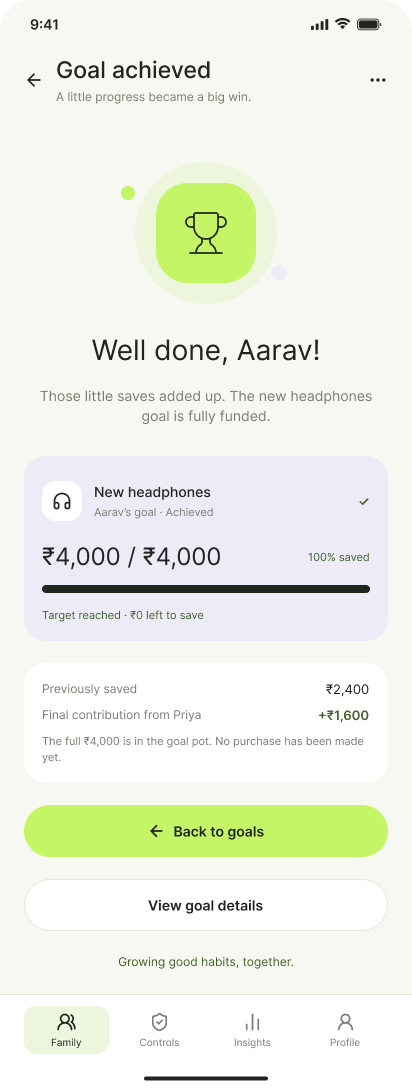
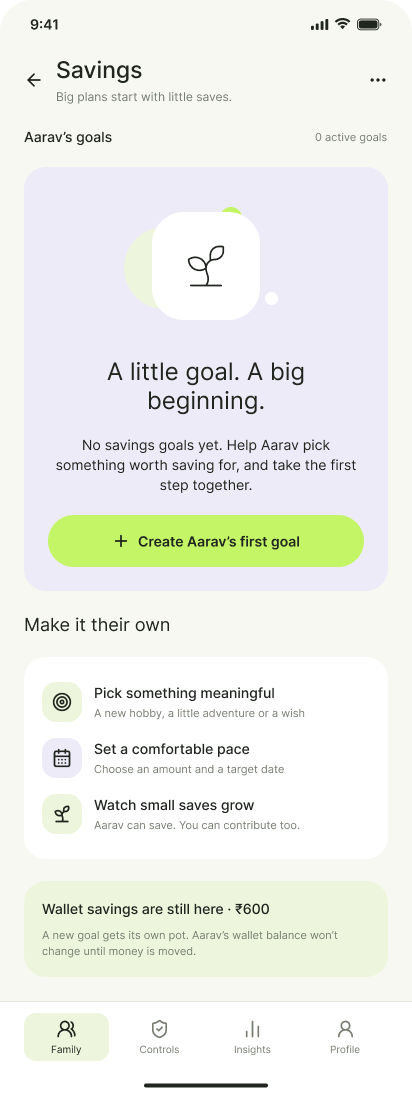
14Empty & Success States

No goals, no activity, no notifications and completed actions.

07

Product decisions that shape the UX.

NOVA is not just about adding fintech features. It is about deciding what information deserves attention at each moment.

Balance before analytics

The teen home answers the immediate question first: how much money is available?

  • Strong numerical hierarchy
  • Quick actions close to the balance
  • Insights remain secondary

Patterns before transactions

The parent dashboard starts with what needs attention and how a child is doing before showing raw activity.

  • Family summary first
  • Child patterns second
  • Detailed activity available when needed

Goals make saving tangible

Saving becomes easier to understand when a number is attached to something the teen actually wants.

  • Target and current amount
  • Visible progress
  • Deadline and contribution rhythm

Approval shows consequences

Parents see what the purchase means for the child's remaining balance before approving.

  • Merchant and reason
  • Current balance
  • Post-purchase balance
08

Design system thinking.

NOVA follows the portfolio's established case-study visual language rather than introducing a separate visual identity: Instrument Sans for display and UI hierarchy, Manrope for body copy, dark ink, neutral paper, restrained glass surfaces and square-edged actions.

Ink
#0B0D12
Paper
#F3F4F6
Text
#11141B
Neutral accent
#C9CCD1

Typography

Instrument Sans + Manrope

Instrument Sans carries large headings, navigation and interface emphasis. Manrope carries supporting copy, metadata and explanatory content.

09 · Cross-platform interaction

Independence for the teen. Confidence for the parent.

A key product decision is the relationship between the two experiences. A teen can work toward a goal while a parent can understand progress. A purchase can be experienced as a simple payment on one side and a contextual approval on the other.

NOVA teen mobile experience visual
10

Trade-offs and trust.

The challenge is giving teens room to manage money while keeping parents informed without making the experience feel over-controlled.

Guidance, not surveillance

Teens get a clear view of their money. Parents see useful patterns and alerts rather than needing to check every transaction.

Make risky actions clear

Payments and approvals should confirm the amount, recipient and impact before completion, with clear error and recovery states if something fails.

11

Research & Validation.

The product addresses teen and parent needs through its problem framing and user flows. The current design is reviewed through scenario walkthroughs, usability heuristics and cross-screen consistency checks. These are design reviews, not claims of completed user interviews or live user testing.

01

Scenario walkthroughs across payment, saving and parent approval flows

02

Heuristic review for hierarchy, clarity, control and error prevention

03

Cross-screen consistency review across the 29-screen product system

No user-testing percentages, adoption figures or revenue impact are claimed without supporting evidence. The next validation step is to test the core flows with teens and parents and use their feedback to refine the product.
12

Development in progress.

Flutter development is underway. Once development is complete, the Android .apk and iOS .ipa builds will be shared for review.

Next

Build and test the core flows.

Prioritise payments, savings goals, parent approvals and key error states, then test them with teens and parents before making product claims.

13

What I learned.

Designing NOVA reinforced that youth fintech is not simply a smaller banking product. The experience has to balance autonomy, comprehension, habit-building and responsible parental involvement.

Make money understandable

Balances and transactions become more useful when the interface explains what they mean and what the user can do next.

Design the relationship

The teen and parent experiences should feel connected without forcing both users into the same interface or level of detail.

Validate with real users

Product decisions should be checked with real users wherever possible, and outcomes should be reported only when supported by evidence.

Designing financial products that teach independence, not just transactions.

NOVA explores how a youth-finance product can connect everyday spending, saving and learning with a parent's need for context and confidence.